

Lemonade Insurance
by Lemonade Insurance
3.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.8
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
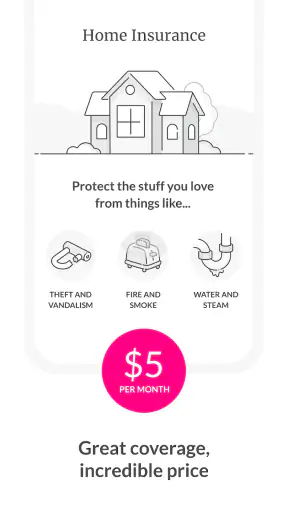
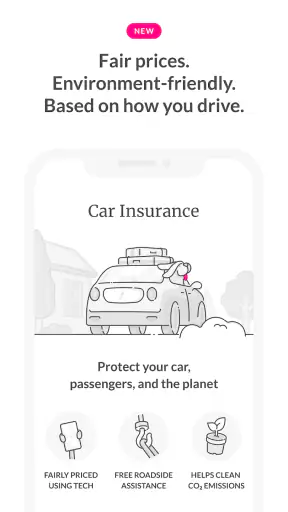
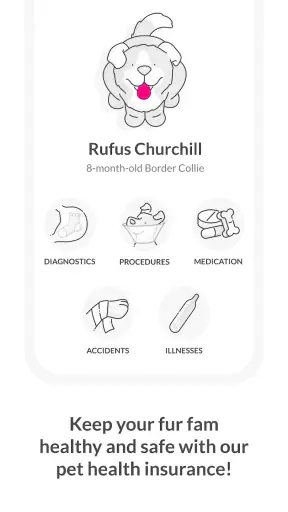
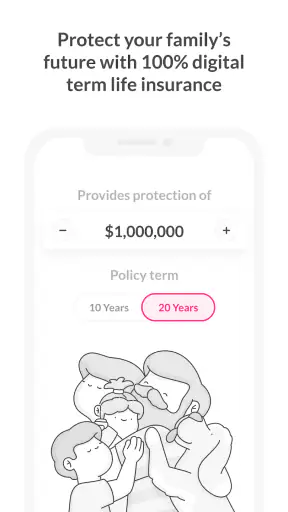
 Analysis by Getfullapps
I approach insurance apps with a fairly simple test: can I understand what I am buying, get a useful quote without wasting an evening, and manage the policy later without having to dig through paperwork? Lemonade Insurance is built around that kind of quick, mobile-first experience. It is a free finance app from Lemonade Insurance, aimed at people who would rather handle an insurance task from a phone than begin with a call or a branch visit.
After spending time with it, my view is positive but conditional. Lemonade Insurance is most appealing when speed, a clean digital process, and low administrative effort matter more to you than comparing every possible insurer through one place. It can make the first step feel much less intimidating, especially if you are arranging cover for the first time. At the same time, insurance is not a purchase where a polished interface should replace careful reading. The app helps simplify the journey, but you still need to check what a policy actually covers before deciding.
How I judged the app before recommending it
My first decision criterion was clarity. A quote that arrives quickly is useful only if I can tell what information shaped it, what I would pay, and what situations are included or excluded. Lemonade’s core promise is a fast quote with little paperwork, so I paid attention to whether the app feels like a practical tool rather than a digital brochure.
The second criterion was convenience after the initial quote. Insurance is easy to ignore until something changes: a move, a new possession, a damaged item, or a question about an existing policy. An app deserves credit when it reduces those small moments of friction, not merely when it looks modern during sign-up.
I also considered the audience. Someone renting a home, protecting personal belongings, or looking for a straightforward way to start an insurance conversation may appreciate this approach. Someone with unusual property, several complex risks, or a strong need to compare many providers may need a more traditional route. Those are not minor distinctions; they determine whether the app feels efficient or restrictive.
The public response gives a useful sense of scale. Lemonade Insurance has an average rating of 3.8 from around 20 thousand ratings, with more than 8 thousand written reviews and over 1 million installs. I would read that as evidence of a substantial user base rather than proof that every customer has the same experience. Insurance apps naturally receive mixed reactions because the quality of an outcome depends on the policy, the claim, the circumstances, and the user’s expectations.
The app is free to install and is marked suitable for Everyone. That does not mean insurance itself is free; the app is the access point for quotes and policy-related activity, while the actual cost depends on the cover and personal details involved. I appreciate that distinction because it prevents a common misunderstanding when browsing finance apps.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The first-use experience and the value of speed
The strongest part of the concept is the reduction of early friction. Instead of starting with a stack of forms or a long phone conversation, I can begin on the phone and work through questions at my own pace. That matters when I am comparing options late in the day, moving between homes, or simply trying to understand whether a policy is worth investigating.
Fast quoting is especially helpful for a renter who has just signed a lease and needs to organize cover before moving in. In that situation, the app can turn an unpleasant administrative job into a short, focused task. I can gather the details I need, review the offer, and decide whether to continue without arranging a separate appointment.
There is a less obvious benefit here: the app encourages me to think about insurance before an emergency. When the process feels accessible, I am more likely to review my belongings, consider replacement needs, and keep relevant information nearby. That habit is more valuable than shaving a few minutes from a quote.
Still, speed can create its own risk. A quick series of screens may encourage people to tap through without checking limits, deductibles, exclusions, or the meaning of an optional choice. My practical advice is to slow down at the point where the quote becomes a real financial commitment. Save the wording, note the figures that matter, and compare the protection rather than comparing only the headline price.
What makes the mobile approach genuinely useful
The app’s main strength is not simply that it is on a phone. It is that the phone becomes the place where I can begin, review, and revisit an insurance decision without recreating the entire process each time. That is a better fit for people who keep documents digitally and prefer self-service to scheduled conversations.
I also like the psychological effect of separating exploration from commitment. A person can investigate a quote when the need first appears, then return after checking household details or discussing the decision with a partner. That is a healthier workflow than making a rushed choice because a call is already in progress.
Another practical insight is to prepare before opening the app. I would make a short inventory of the property or belongings I want to protect, estimate replacement values, and identify any details that could affect the quote. The app may be quick, but accurate answers still depend on thoughtful preparation. A few minutes spent gathering information can prevent an attractive quote from being based on an incomplete picture.
For existing customers, the value is likely to come from having insurance activity in one familiar place rather than searching through email or paper files. I find that especially useful when a question arises unexpectedly. However, I would still keep important policy documents somewhere I can access independently. An app is convenient, but a second copy of key information is sensible whenever a financial or claims issue matters.
Where the usual alternatives may fit better
The main alternative is the conventional insurer website or a direct conversation with an insurance representative. That route may suit someone who wants a person to explain terminology, discuss unusual circumstances, or walk through several coverage choices. If I am uncertain about what a policy means, the ability to ask detailed questions can be more valuable than a faster interface.
Comparison services are another category. They can be a better match when my priority is seeing offers from multiple providers in one research session. Lemonade’s focused experience may feel cleaner, but a focused experience is not the same as a broad market comparison. If price-shopping across many companies is central to my decision, I would use a comparison route as well rather than assuming one app represents every suitable option.
A local broker can also have an advantage for complicated needs. Someone with several properties, specialist possessions, business-related equipment, or a history that requires careful explanation may benefit from human guidance. I would not choose a streamlined app simply because it is easier to open if the situation itself is difficult to describe.
There is a trade-off between simplicity and breadth. Lemonade Insurance is designed to make the journey approachable, while a traditional process may expose more detail earlier. Neither approach is automatically superior. I prefer the app when my needs are reasonably straightforward and I am comfortable checking the wording myself. I prefer a person or a broader comparison process when the consequences of misunderstanding a detail are high.
Small frictions that can change the decision
My biggest reservation is that digital convenience can make insurance appear simpler than it really is. A pleasant flow does not remove the need to understand claim conditions or policy boundaries. If I am the type of customer who tends to accept the first clear-looking offer, I would build in a deliberate pause before buying.
There is also a practical dependence on comfort with self-service. The app is a poor fit if I dislike entering personal information on a phone, want extensive verbal guidance, or regularly need explanations tailored to unusual circumstances. In those cases, the time saved at the start may be lost later through uncertainty.
I would also avoid judging the experience only by the quote. A lower initial cost can be less attractive if the cover does not match the value of my belongings or the risks I actually face. The useful comparison is between like-for-like protection, including the amount I would have to pay myself after a covered event and the situations that fall outside the policy.
The app’s current version is 9.36.1 and it requires Android 8.0 or later. That makes checking device compatibility worthwhile before planning to use it as the main way to manage insurance. On a supported phone, the experience should be evaluated alongside the broader policy terms, not in isolation from them.
Making the switch without creating new work
Moving from a traditional insurer to a mobile-first option is not just a download decision. I would first collect my current policy details, renewal date, coverage limits, and any recent claims information. Then I would compare the existing protection with the new quote line by line. This is the least glamorous part of switching, but it is where many false savings are discovered.
I would never cancel an existing policy merely because a new quote looks cheaper. First confirm that the replacement cover is active, check whether timing creates a gap, and make sure the named people, address, and protected items are correct. The app can make obtaining a new quote easier, but it cannot make a coverage gap harmless.
A useful switching test is to imagine a claim rather than a purchase. If a valuable item were damaged tomorrow, would I know where to find the policy, what evidence might be relevant, and what financial responsibility would remain with me? If I cannot answer those questions, I need more reading or human assistance before changing providers.
For renters and people with uncomplicated needs, the switch may be relatively manageable because the mobile workflow removes much of the usual back-and-forth. For homeowners with layered protection or anyone whose circumstances have changed recently, I would take more time and consider speaking with an adviser. The app is a strong starting point, but it should not be treated as a substitute for judgment.
Who should install it, and who should skip it?
I would recommend trying Lemonade Insurance if I want a fast way to explore insurance, prefer handling routine tasks from a smartphone, and am willing to read the policy details carefully. It is particularly attractive for a renter or a first-time buyer who feels put off by paperwork and wants a more approachable starting point.
I would also suggest it to someone who values flexibility in the research stage. Being able to begin a quote without committing to a phone appointment makes it easier to ask, “What would this cost for my situation?” That can be useful even when the final decision involves comparing another provider.
I would skip it as my only research method if I need highly specialized cover, want a broker to interpret complicated risks, or consider a multi-provider comparison essential. I would also hesitate if I know I will not read exclusions and limits. In that case, a more guided process may protect me from making a decision based on convenience alone.
My everyday recommendation is to use the app in two passes. On the first pass, gather a quote and learn what information it requests. On the second, return with an inventory and compare the actual protection against my current arrangement or another serious alternative. That two-step approach keeps the app’s speed while reducing the chance of a rushed purchase.
My recommendation after using it
Lemonade Insurance succeeds at making the beginning of insurance feel less burdensome. Its free app, quick quote-focused approach, and mobile self-service design are meaningful advantages for people who want to get organized without paperwork dominating the process. The developer, Lemonade Insurance, has clearly positioned the product for a digital audience, and the scale of its adoption shows that this style of insurance management appeals to many users.
My recommendation is therefore positive, with an important condition: use it as a decision tool, not as a shortcut around understanding the policy. I would install it when I wanted a convenient quote or a simpler way to start managing cover. I would compare the result with my needs, and I would move to a traditional insurer, comparison service, or broker when my circumstances demanded broader choice or more explanation.
For me, the app earns its place because it removes unnecessary effort without pretending that insurance itself is effortless. That balance is the reason I would recommend it to a friend with straightforward needs. If you are comfortable taking responsibility for the final reading and comparison, it is a practical finance app worth trying. If you need specialist advice, the usual alternatives may be the better investment of your time.
Pros
- Fully digital policy management through the mobile app.
- Fast, convenient claims filing from your phone.
- Social impact model supports charitable causes.
- Simple coverage options for renters and homeowners.
- Transparent pricing with no traditional agent commissions.
Cons
- Availability is limited to selected countries and U.S. states.
- Not all policy types are offered in every location.
- Some claims may require additional documentation or review.
- Rates can vary significantly by location and personal profile.
- Phone support may be less immediate than traditional insurers.
FAQs for Lemonade Insurance
What is Lemonade Insurance, and what types of coverage does it offer?
Lemonade is a digital insurance platform that allows eligible customers to purchase and manage policies through its mobile app or website. Depending on your location, it may offer renters, homeowners, condo, pet, life, car, and other insurance products. Availability, policy options, limits, deductibles, exclusions, and pricing vary by state or country, so review the actual quote and policy documents carefully before buying.
How does the Lemonade Insurance app work when getting a quote or filing a claim?
The app is designed to handle most insurance tasks digitally. You can answer questions to receive a quote, select coverage, pay premiums, access policy documents, update certain details, and report a claim from your phone. Claims usually require information about what happened and supporting evidence such as photographs, receipts, or reports. More complex cases may be reviewed by a claims professional.
Is Lemonade Insurance available everywhere, and can anyone sign up?
No. Lemonade’s availability depends on the insurance product and your location. Coverage is offered only in selected states or countries, and eligibility can also depend on factors such as the property address, vehicle, pet, age, driving history, or underwriting requirements. Before downloading or applying, check whether Lemonade supports your area and the specific type of insurance you need.
How much does Lemonade Insurance cost, and are there additional fees?
There is no single price for Lemonade Insurance because premiums are calculated using details such as your location, selected coverage, deductible, limits, personal information, and the type of policy. Some policies may also include service charges, taxes, or other applicable costs. The app displays pricing during the quote process, but compare the complete policy—not only the monthly premium—with other providers.
What should I know about Lemonade’s claims process and policy limitations?
Lemonade promotes a convenient digital claims experience, but approval is not automatic and depends on the terms of your policy. Claims may be denied or limited because of exclusions, deductibles, coverage caps, missing documentation, late reporting, or circumstances outside the policy. Read the declarations page and full policy wording, keep proof of ownership, and contact support or the assigned claims team if you need clarification.

Lemonade Insurance
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via feedback@lemonade.com, visit https://www.lemonade.com, or review their https://www.lemonade.com/privacy-policy/.










